LOCKED RATE
${RATE_TD_RANGE}.
Your rate is locked for your entire term. No surprises, no fluctuations.
Lock in a fixed interest rate between ${RATE_TD_RANGE}¹. Get a higher rate by selecting a longer term. Grow your money for your next milestone.
What is Gainbridge: Flex℠?
Gainbridge Flex annuity is a non-tax-deferred fixed-rate annuity account you open online. Lock the money you want at guaranteed rates for the term(s) you select¹, and whatever you don't lock still earns interest in your Cash Wallet. Unlike a CD, one account can hold as many terms as you want, each with its own rate and end date, so you never have to reapply just to add money.
Open an account for as little as $100, and add money anytime starting at $50. Access your savings before retirement age with no IRS penalty. Do it yourself, and call us if you want.
| U.S. Treasury Bill | Certificate of Deposit | High Yield Cash Management Account | ||
|---|---|---|---|---|
| Rate | ${RATE_TD_1YR_LOW}, fixed for 1-yr term² | 4.48%, 1-yr maturity³ | ~3.92% APY, fixed for 1-yr term⁴ | ~3.46%, variable⁵ |
| Risk to Principal | None, if held to term⁶ | None, if held to maturity⁷ | None, if held to maturity⁸ | None⁹ |
| Minimum to Start | $100 | $100 | Varies by provider | Varies by provider |
| Add Funds Later | Yes, anytime¹⁰ | No, new purchase required | No, new CD required | Yes |
| Access to Funds | Cash Wallet + 10% Annual Free Withdrawal¹¹ | Locked to maturity; tradable on secondary market before then¹² | Locked until maturity; early withdrawal penalty¹³ | Fully liquid |
| Returns | Up to ${RATE_HIGHEST} |
|---|---|
| Average Losses | None |
| Volatilty | None |
| Principle Protected | Yes, if invested for the entire duration |
| Fees | None, if invested for the entire duration |
| Liquidity | 1 to 10 years |
| High Yield Cash Management Accounts | |
|---|---|
| Returns | Around 4.3% |
| Average Losses | None |
| Volatilty | None |
| Principle Protected | |
| Fees | Usually waived with a minimum balance requirement |
| Liquidity | Fully liquid |
| Certificate of Deposit | |
|---|---|
| Returns | Around 4.0% |
| Average Losses | None |
| Volatilty | None |
| Principle Protected | Yes, if invested for the entire duration |
| Fees | Usually none, if invested for the entire duration |
| Liquidity | Not liquid for length of term |
| Broad Stock Market EFTs | |
|---|---|
| Returns | 10% annualized nominal return over the long run (many decades) |
| Average Losses | - 13% during downturns |
| Volatilty | High |
| Principle Protected | None |
| Fees | Usually none, for most platforms. |
| Liquidity | Very liquid |
Open an account for as little as $100. Add money whenever you have it, no set schedule, no new application each time. Each deposit locks its own rate, on its own timeline.
The rate for the term you choose and fund is locked in, and interest is credited daily. It doesn't move with the market. You'll know the exact amount you're building toward, and when you'll have it.
Terms run as short as 1 year (1 to 9 in California). Each calendar year, you can take out up to 10% of what's in a term with no fee, so your money isn't locked away for decades to reach it.
| Under $100k | $100k and over | |
|---|---|---|
| 1 year | ${RATE_TD_1YR_LOW}${RATE_TD_1YR_CA_LOW} | ${RATE_TD_1YR_HIGH}${RATE_TD_1YR_CA_HIGH} |
| 2 years | ${RATE_TD_2YR_LOW}${RATE_TD_2YR_CA_LOW} | ${RATE_TD_2YR_HIGH}${RATE_TD_2YR_CA_HIGH} |
| 3 - 4 years | ${RATE_TD_3YR_LOW}${RATE_TD_3YR_CA_LOW} | ${RATE_TD_3YR_HIGH}${RATE_TD_3YR_CA_HIGH} |
| 5 - 6 years | ${RATE_TD_5YR_LOW}${RATE_TD_5YR_CA_LOW} | ${RATE_TD_5YR_HIGH}${RATE_TD_5YR_CA_HIGH} |
| 7 - 9 years | ${RATE_TD_7YR_LOW}${RATE_TD_7YR_CA_LOW} | ${RATE_TD_7YR_HIGH}${RATE_TD_7YR_CA_HIGH} |
| 10 years | ${RATE_TD_10YR_LOW}${RATE_TD_10YR_CA_LOW} | ${RATE_TD_10YR_HIGH}${RATE_TD_10YR_CA_HIGH} |
Put money in. Watch it grow. Get to your Cash Wallet anytime.
Select your term length and see your rate upfront. Know exactly what you're
locking in.
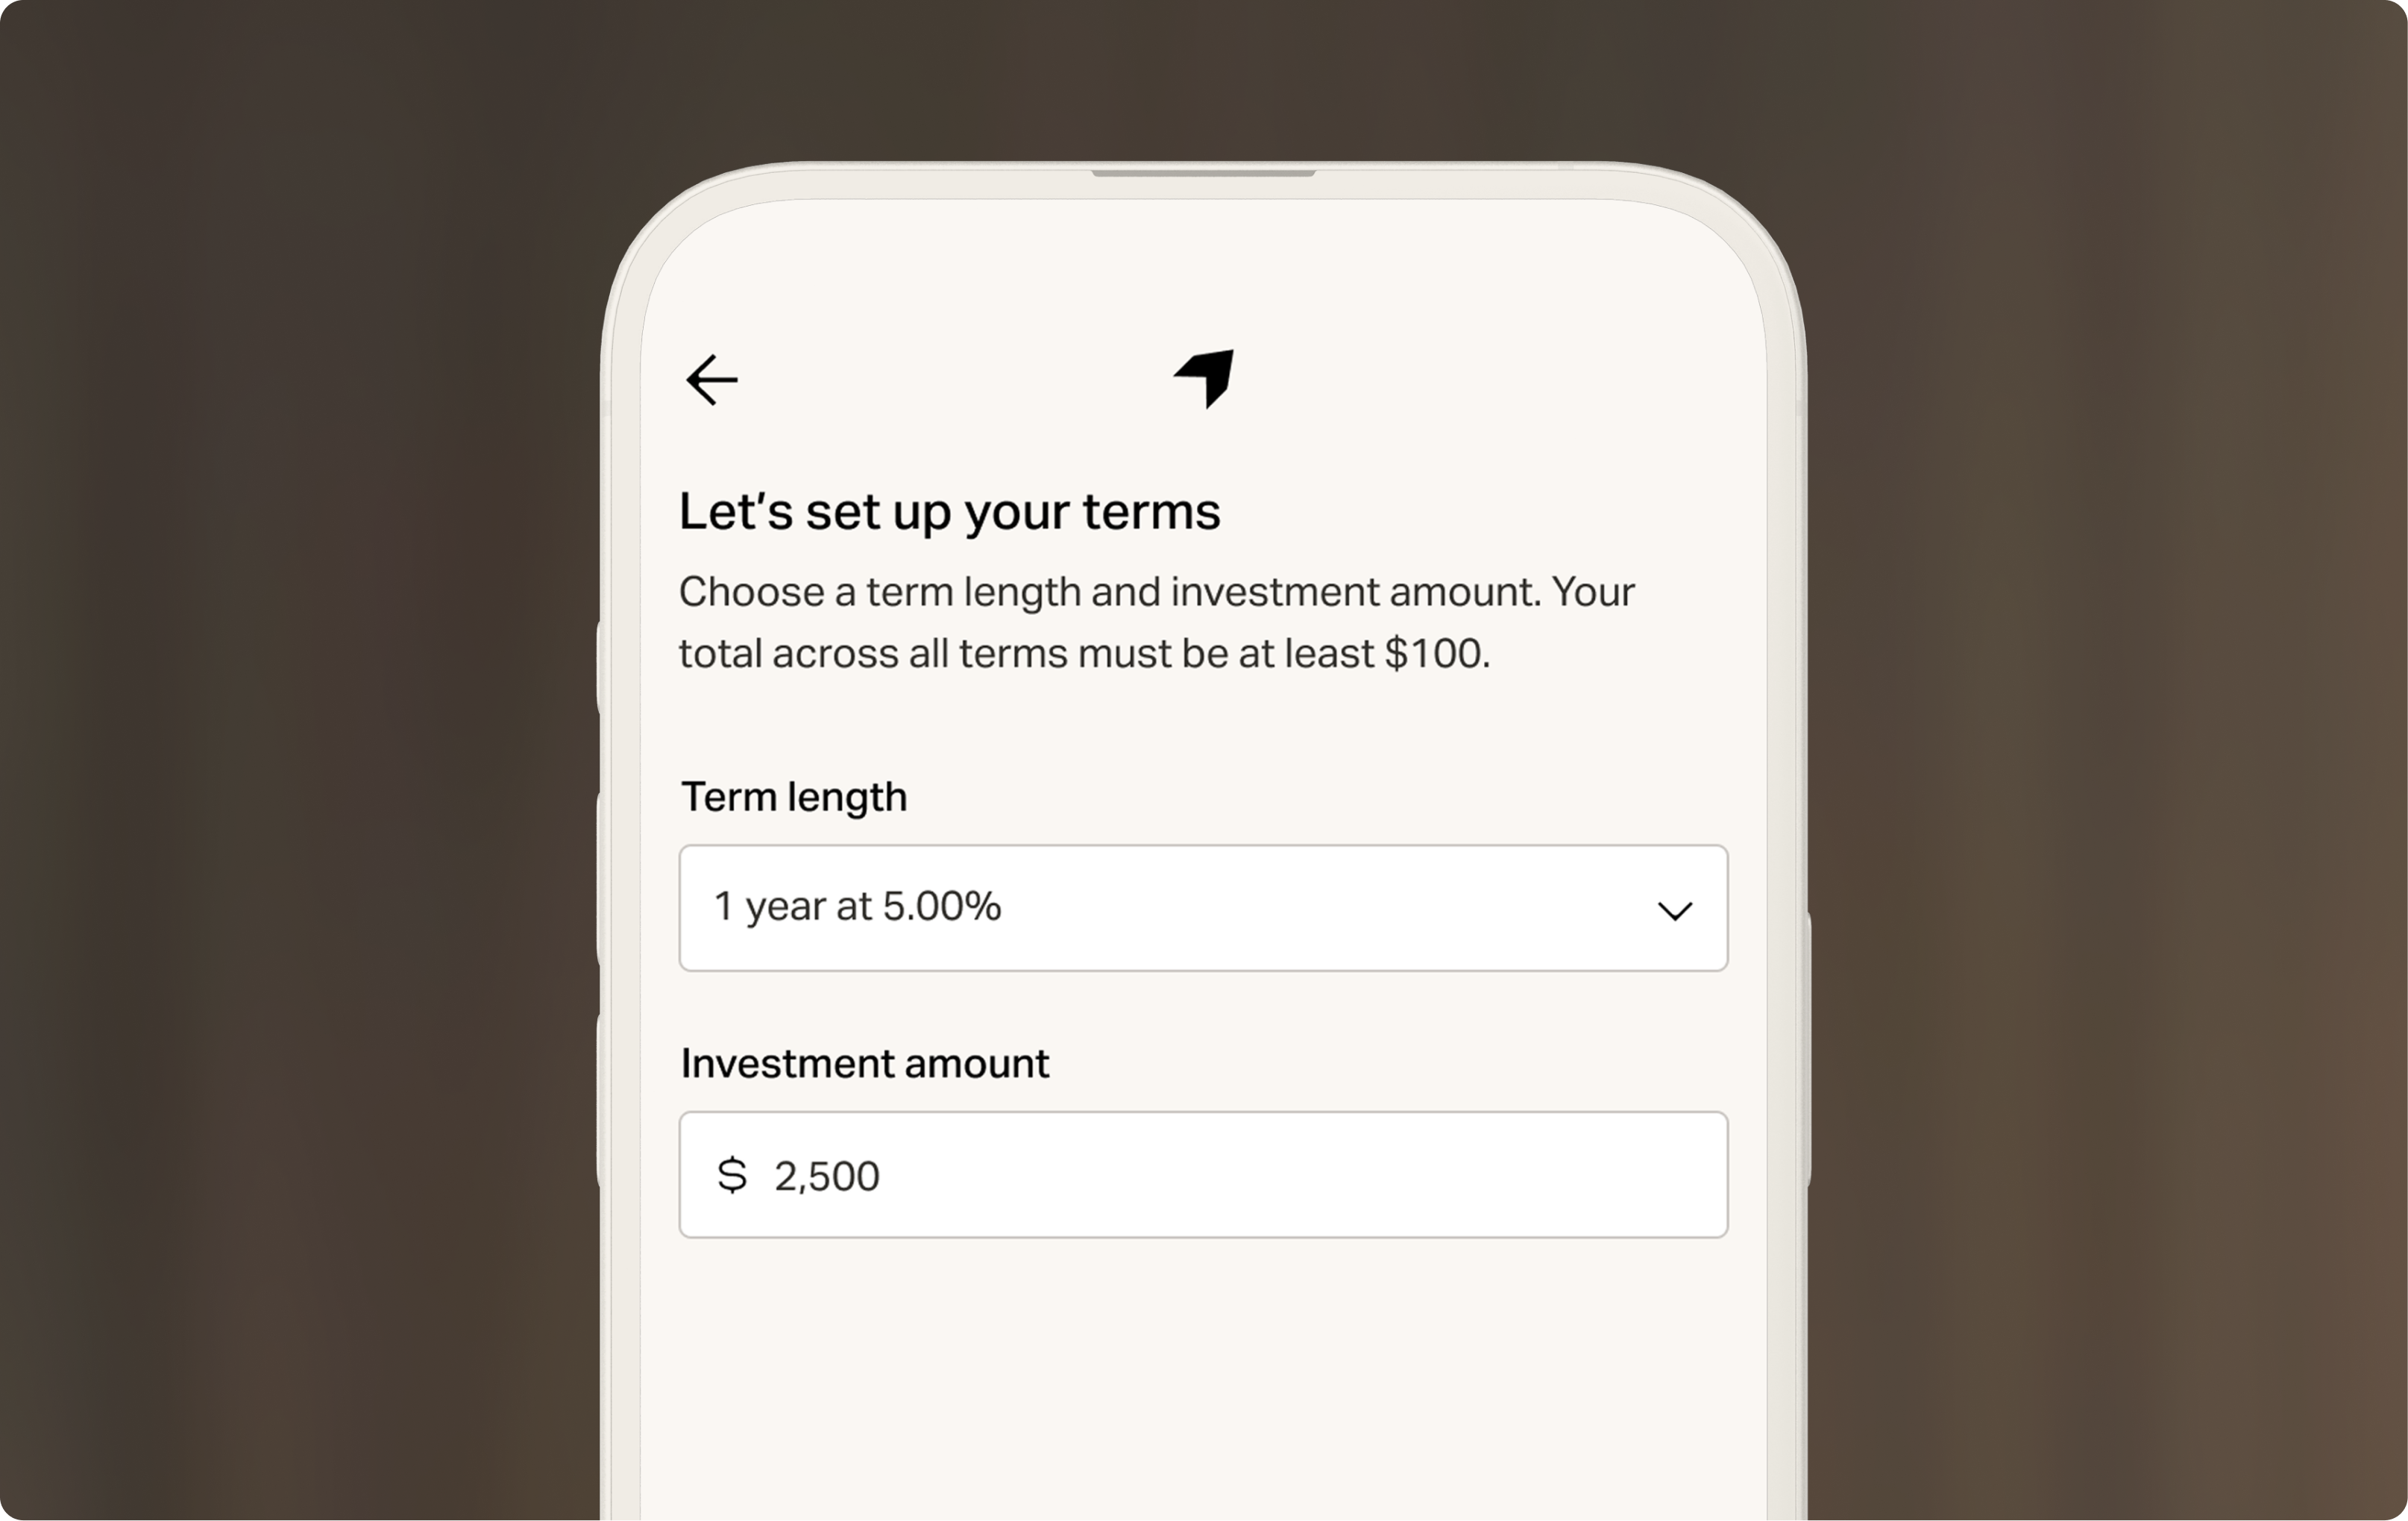
Split a deposit between locked terms and your Cash Wallet. Add more to your account anytime, no application.
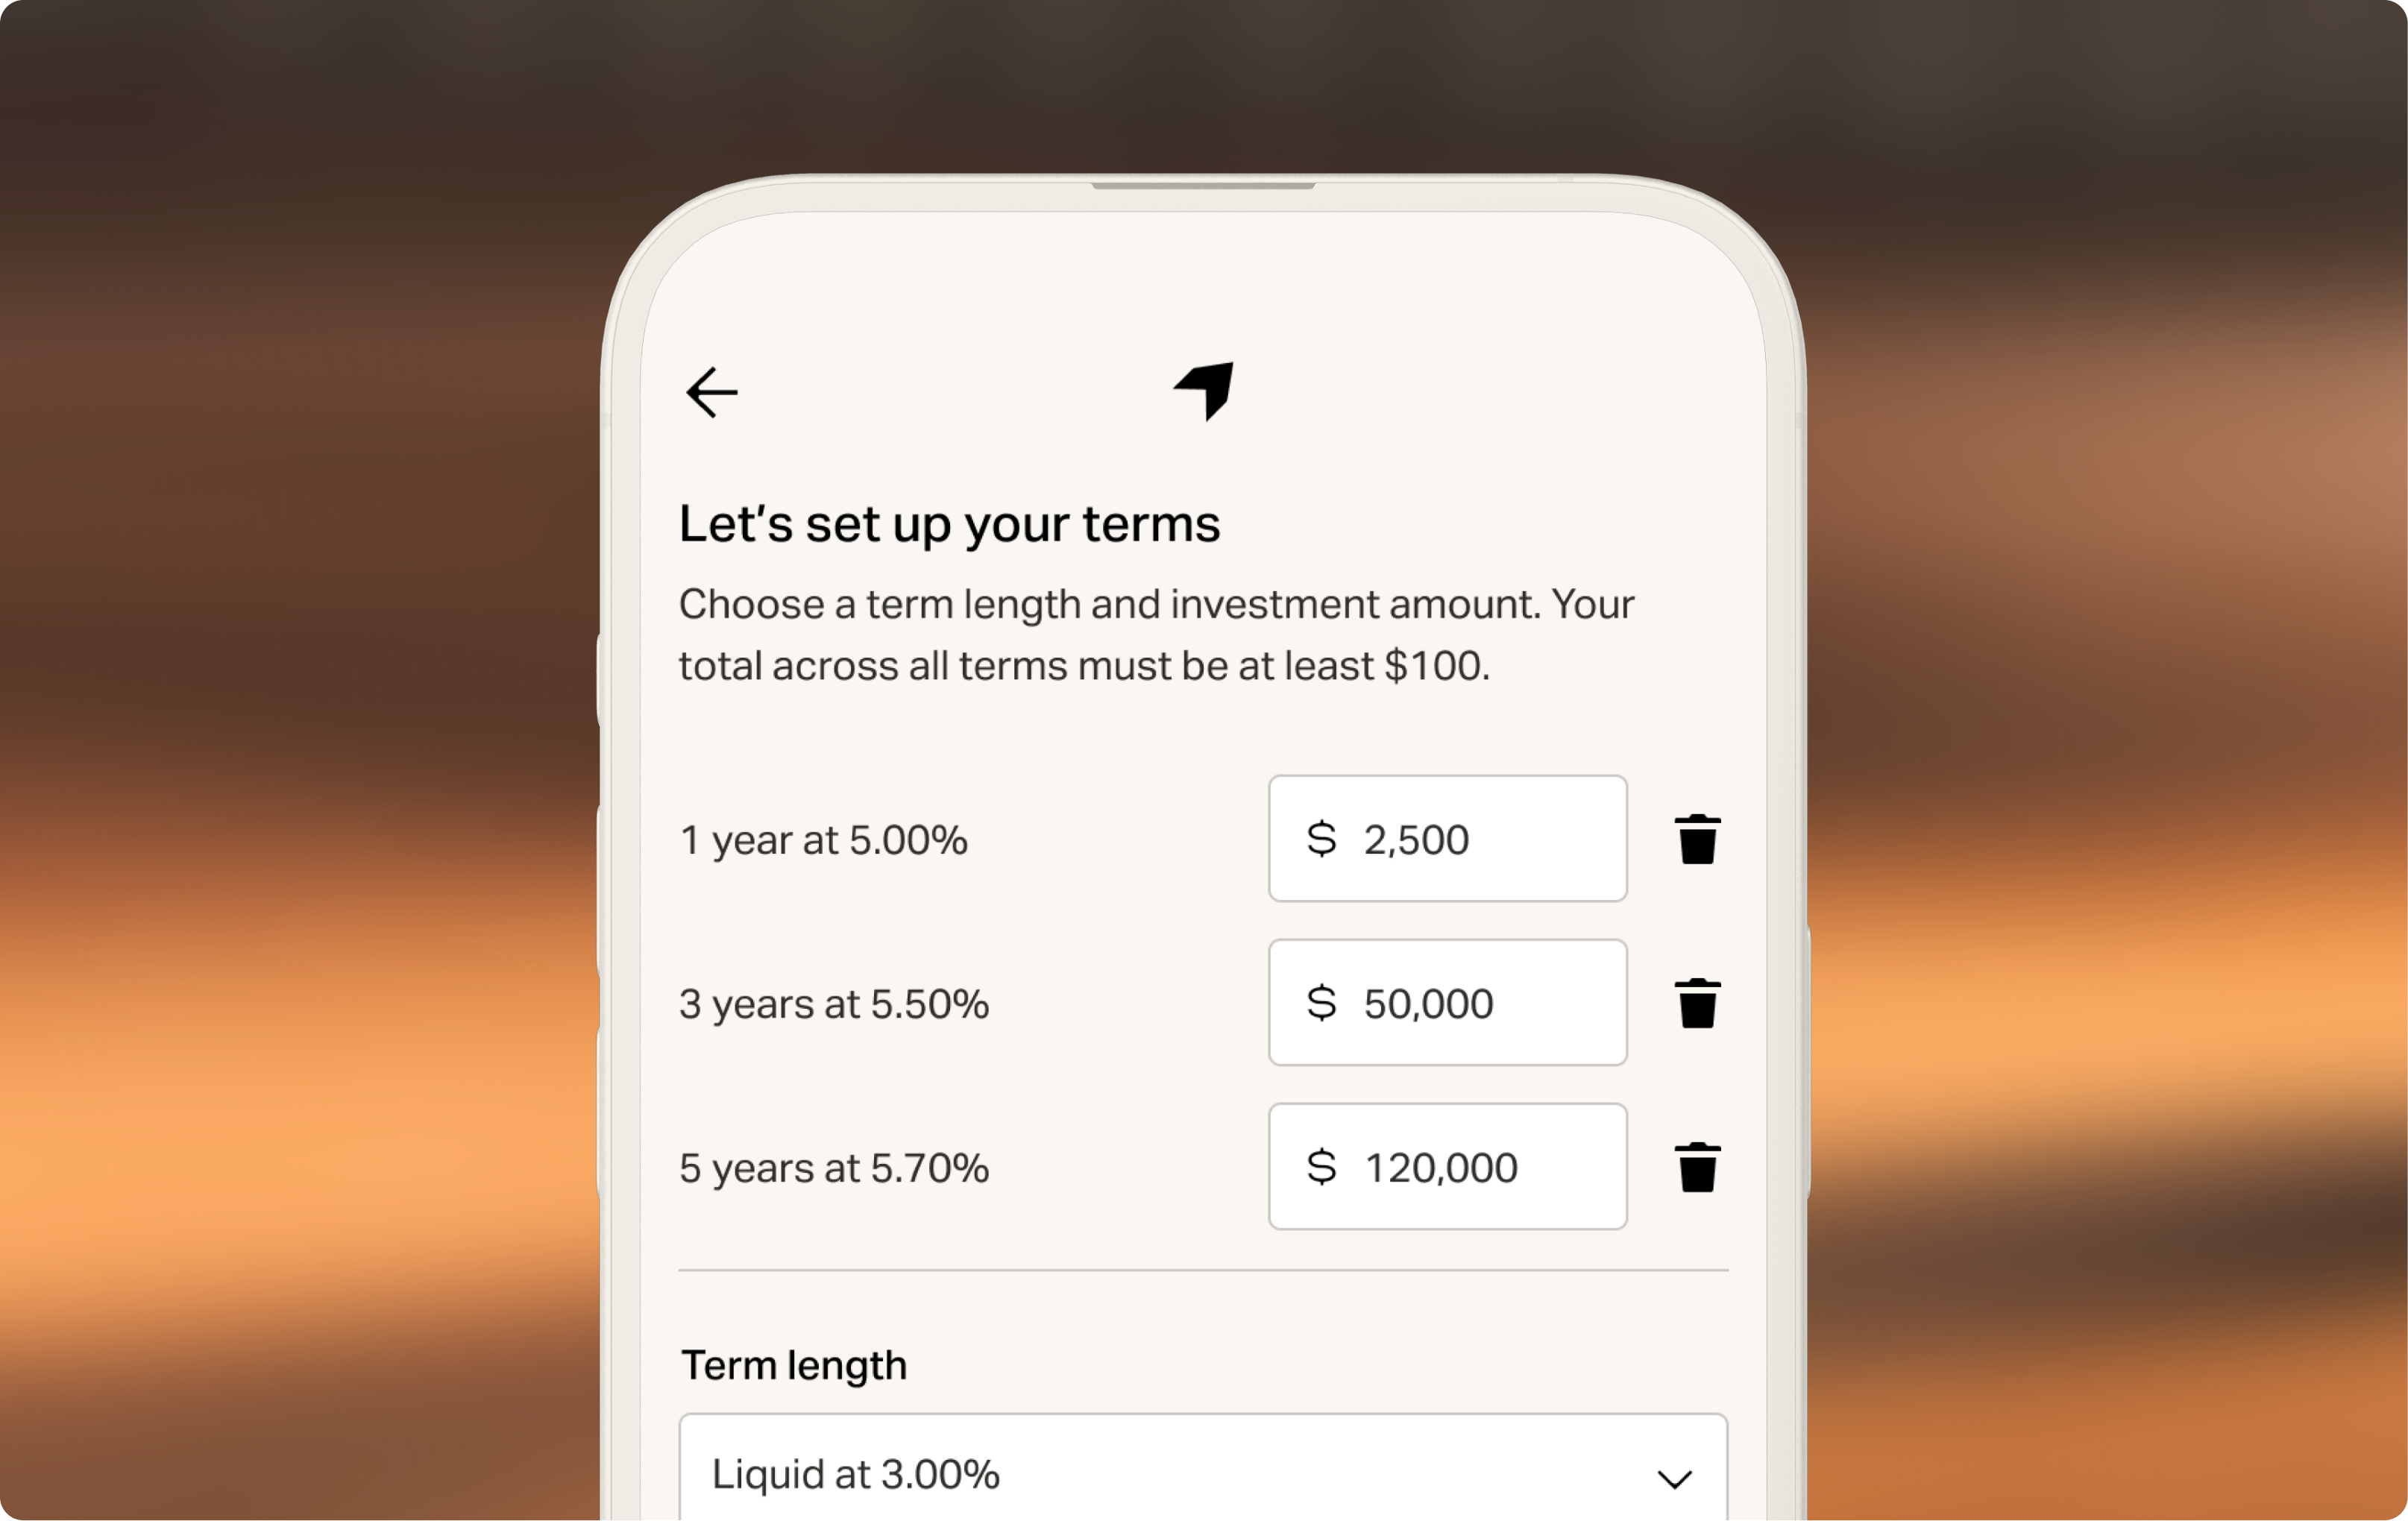
Lock in a rate for each term you choose¹⁵, then check in anytime to watch it grow toward that term's end.

Here are just a few reasons people love Gainbridge.
Have questions about our products or your account? Fill out the form, and one of our expert team members would love to help you.
Quick answers to get you started. Visit our full FAQ page for more.
If you like the certainty of a guaranteed fixed rate but don't want to lock every dollar into one term, Flex may be a good fit. It can work well if you're saving toward a goal a few years out — even retirement — without the age-based penalties or required withdrawals that come with IRA-style accounts. In exchange, your interest is taxed each year. It can also be a great fit if you'd rather add money on your own schedule rather than all at once, if you like splitting savings across different terms — sometimes called laddering — or if you just want to avoid market swings altogether.
Flex may not be the right choice if you might need more than your free withdrawal amount before a term ends, because early withdrawals can be subject to an early withdrawal fee and a market value adjustment. If you want your interest to grow tax-deferred, consider Retirement Flex.
You can contribute once and leave it. Adding is entirely optional. If you want to later, you can make another deposit anytime, starting at $50, into either a new term or the Cash Wallet within the same Flex contract. One thing to know: if your Contract Value stays below $2,500 and you go two full years without adding any funds, Gainbridge may choose to close the contract. We’ll notify you X days in advance, and adding money before then keeps your contract open. So if you’re starting small, keep that in mind before deciding to never revisit it.
Yes. One deposit, multiple destinations — some into a term, some into the Cash Wallet, in whatever split you want, as long as your percentages add up to 100% and are whole numbers (no fractions like 33.3%).
Depends on whether you have Gainbridge: FlexSM or Gainbridge: Retirement FlexSM. Flex is taxable as you go — the interest credited to your annuity each year counts as taxable income whether or not you touch it. Retirement Flex is tax-deferred, so you don't owe anything until you withdraw, and then it follows the rules of whichever type you picked (Traditional, Roth, or Non-Qualified). Since this affects your tax return directly, talk to a tax advisor about how it lands for you specifically.
Flex is a taxable account, so it doesn't carry an IRA-style age penalty — though pulling money from a Flex term before it matures can still trigger a surrender charge, same as any early withdrawal. If you're weighing Flex against Retirement Flex: pulling money from a Retirement Flex account before 59½ can trigger a 10% IRS early withdrawal penalty on top of ordinary income tax, and pulling it before a term matures can add a surrender charge on top of that. Worth running the numbers with a tax advisor before you commit either way.
9 Min read
Not sure about investing in an annuity? Read through the pros and cons of annuities to decide whether these products suit your financial plan.

8 Min read
New generations aren’t buying annuities like their parents, and their expectations are reshaping the market. Read Gainbridge's report on the shift to modern solutions.